Safeguarding Your Spark: The Definitive Guide to Fire Protection Contractor Insurance
30
Aug
2026
Author:
Michael Kovalev
Why Specialized Coverage is Critical for Massachusetts Contractors
Fire protection contractor insurance is specialized coverage for contractors who install, service, and maintain fire suppression and safety systems. It protects against the unique risks of this life-saving work.
Quick Answer: What Fire Protection Contractors Need to Know
General Liability: Covers property damage & bodily injury ($1M/$2M limits).
Professional Liability (E&O): For design errors & failure to perform claims.
Workers' Compensation: Required in MA for employees (Class Code 5188).
Commercial Auto: Covers vehicles & equipment in transit.
Average Cost: Starts at $69/month; minimum premiums from $650-$25,000.
Key Endorsements: Additional Insured, Waiver of Subrogation, Per Project Aggregate.
As one contractor noted, "A fire can spread out of control within 60 seconds." When a fire protection system fails, the financial consequences can be devastating. This high-stakes reality makes specialized insurance essential.
The construction boom in Massachusetts cities like Newton, Wellesley, and Brookline offers great opportunities, but this work involves unique exposures that standard policies miss. Risks like system design errors or water damage from malfunctioning sprinklers require custom coverage.
With stringent state building codes, proper insurance isn't just smart—it's often legally required. Whether you're installing systems in Needham or servicing equipment in Natick, the right protection is vital.
Fire protection contractor insurance terms simplified:
Just as you wouldn't install a single sprinkler head and call it a complete system, your fire protection contractor insurance shouldn't be a single policy. It's a suite of coverages engineered to protect your business from every angle. Each policy handles specific risks, creating a comprehensive safety net for your assets.
The Unique Risks Faced by Fire Protection Contractors
In the business of protecting lives and property, the stakes are incredibly high. A single mistake can lead to catastrophic damage or injury. Your work creates unique risks that typical contractor policies don't cover:
System Failure, Design Errors, & Installation Mistakes: A system that fails to activate during a fire in a Brookline office can lead to millions in liability claims. A design miscalculation or an improper pipe fitting can result in inadequate protection, code violations, or immediate water damage during testing.
Water Damage from Sprinklers: Ironically, one of the most common claims comes from the systems designed to help. Malfunctioning or accidentally triggered sprinklers can cause extensive water damage.
Bodily Injury & Property Damage: Standard job site risks, like an employee damaging property in a Needham facility or a client slipping and falling, are always present.
Faulty Equipment & Completed Operations: You can be held liable if a component you installed proves defective, even if it wasn't your fault. Furthermore, your responsibility doesn't end when the job is done. If a system fails months or years later, you could still face a claim, making completed operations coverage critical.
Essential Coverages for Your Fire Protection Business
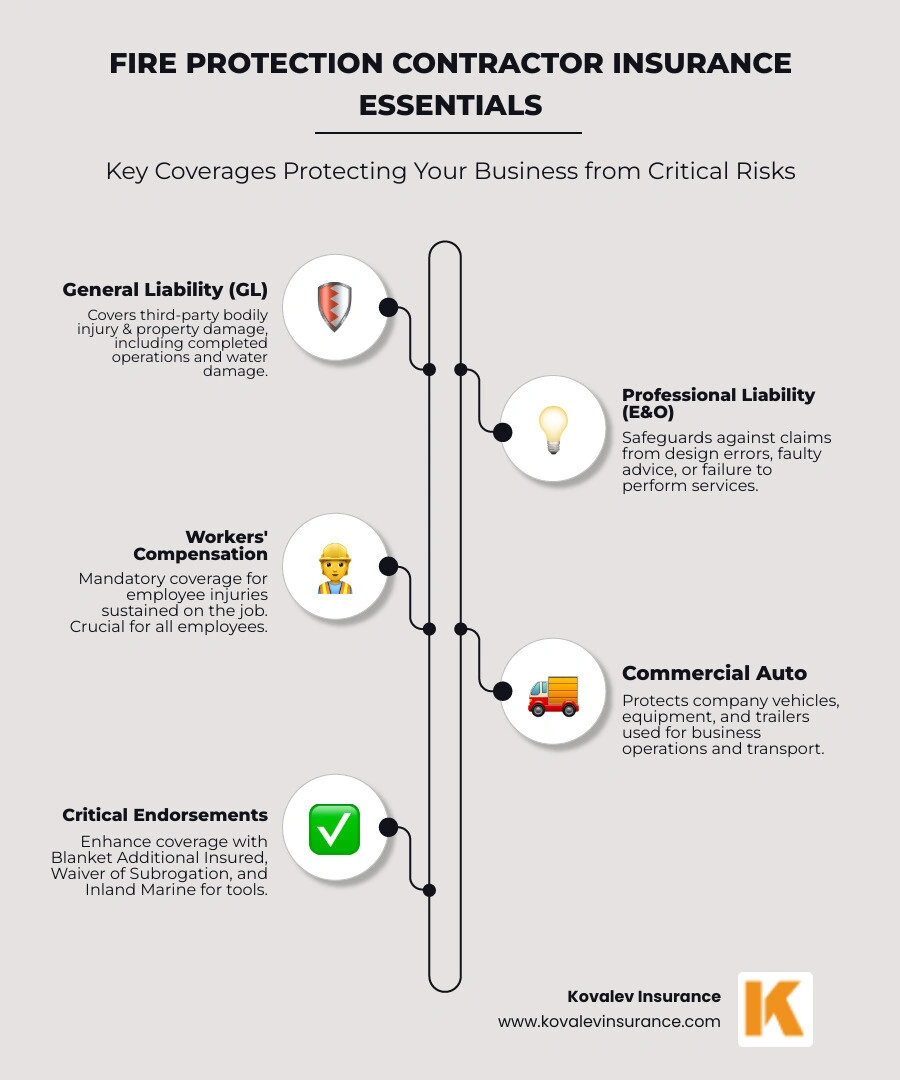
Your insurance program needs three core coverages to be stable: General Liability, Workers' Compensation, and Commercial Auto.
General Liability Insurance is your foundation, covering bodily injury or property damage your work causes to others. If your crew floods a Belmont restaurant during an upgrade, this policy covers the repair costs. Most Massachusetts contractors carry $1M per occurrence / $2M aggregate limits, as often required by contracts. For more on local costs, see our guide on General Liability Insurance MA Cost.
Workers' Compensation Insurance is required by Massachusetts law if you have employees. It pays for medical expenses and lost wages for injured workers. Fire protection contractors fall under class code 5188, reflecting the specific risks of the trade. Learn more at our Worker Compensation Insurance Mass page.
Commercial Auto Insurance protects the vehicles that transport your crew and expensive equipment across Greater Boston. It covers liability in an accident and can also cover damage to your own vehicles and the tools inside.
The Critical Role of Professional Liability (E&O) Insurance
General Liability covers physical damage, but what about financial loss from your professional advice or design? That's where Professional Liability Insurance, or Errors & Omissions (E&O), comes in.
Imagine you design a system for a Natick lab. The installation is perfect, but six months later a fire causes major damage because the system fails to activate due to a design flaw. Your General Liability policy may not cover this; the claim stems from a failure of your professional services, which is an E&O matter.
This coverage is crucial for:
Design-build risks: Protects against errors when you are responsible for both designing and installing systems.
Consulting errors: Covers financial losses if your advice on system types or safety protocols is incorrect.
Failure to perform: This vital coverage (also called efficacy coverage) protects you if your system simply doesn't work as intended, even without an obvious installation mistake.
For any contractor involved in design or consulting, Professional Liability is essential. Explore more at our Professional Liability Insurance Mass page.
Blanket Additional Insured: Automatically extends coverage to any general contractor or property owner you're contractually required to, saving time and hassle.
Waiver of Subrogation: Prevents your insurer from suing other parties involved in a loss, a common contractual requirement that smooths over disputes.
Per Project Aggregate: Gives each major project its own separate liability limit, offering better protection on large commercial jobs.
Inland Marine: Protects your valuable tools and equipment while in transit or at a job site, where standard property insurance doesn't.
Surety Bonds: Often required for public or large commercial jobs, these bonds guarantee you'll complete the work (performance bond) and pay suppliers (payment bond).
Cyber Liability: Covers costs related to data breaches, which is critical if you store client information or use digital design software.
Pollution Liability for mold/fungus: A sprinkler leak can lead to mold. This endorsement covers remediation costs, which are typically excluded from General Liability.
Navigating Costs, Compliance, and Choosing Your Partner
Understanding your coverage is half the battle; the other half is navigating costs, compliance, and finding the right insurance partner. You need an expert who knows that installing sprinkler systems in Newton or servicing extinguishers in Natick involves specialized risks.
There's no single price for fire protection contractor insurance. Average costs start around $69 per month, but your final premium depends on several factors:
Location: Operating in dense urban areas of Greater Boston presents different risks than working in suburban Needham or Belmont.
Operation Size: A solo contractor will pay less than a company with 20 employees handling large design-build projects. More employees and larger revenue increase exposure.
Services Offered: Designing complex systems for industrial facilities in Brookline carries more risk (and requires higher Professional Liability limits) than installing residential sprinklers.
Claims History: A clean record lowers your costs, while a history of frequent or major losses will increase them.
Coverage Limits: Basic $1M General Liability costs less than higher limits or a multi-million dollar Umbrella policy. Minimum premiums can range from $650 to over $25,000 for comprehensive programs.
Meeting Contractual and Massachusetts State Requirements
You must meet specific legal and contractual insurance obligations to operate legally and win jobs.
State Law: In Massachusetts, Workers' Compensation is mandatory if you have any employees. Fire protection contractors use Class Code 5188.
Contractual Requirements: General contractors and property owners will require proof of specific coverage, typically $1M/$2M General Liability limits, Workers' Comp, and Commercial Auto. They will also ask to be named as an additional insured and for a waiver of subrogation.
Certificates of Insurance (COI): Be prepared to provide COIs constantly. This document is your proof of coverage for new projects, contract renewals, and licensing.
Finding the Right Insurance Partner in the Boston Area
Choosing an insurance agent is like choosing a business partner. You need someone who understands your industry's unique challenges.
Look for an agent with:
Industry Expertise: They should know the difference between wet and dry systems and understand why you need failure-to-perform coverage.
Local Knowledge: An agent familiar with the Greater Boston market, from Wellesley to Natick, knows the local codes and which carriers work best for Massachusetts contractors.
Risk Management & Claims Support: A great partner helps you prevent claims and advocates for you when one occurs, working with carriers who handle claims fairly and promptly.
At Kovalev Insurance, we specialize in the needs of contractors like you. We know fire protection contractor insurance is about protecting the business you've built. We take the time to understand your operations, whether you're working on residential jobs in Newton or complex commercial projects in Boston, to build a policy that provides real security.