Blog Content

24
Aug
2026
What is HO6 insurance? It's a specialized homeowners insurance policy for condominium and co-op unit owners. An HO6 policy protects the interior of your unit ("walls-in" coverage), your personal belongings, and your liability. It's designed to fill the coverage gap left by your condo association's master policy, which covers the building's exterior and common areas.
Quick Answer: HO6 Insurance at a Glance
When you buy a condominium in Massachusetts—whether in Newton, Brookline, or Wellesley—you own the inside of your unit but share responsibility for the building. Your condo association's master policy protects shared spaces, but it typically stops at your unit's unfinished walls. Everything inside—flooring, cabinets, personal belongings, and your liability—is your responsibility to insure. Without an HO6 policy, a burst pipe, a kitchen fire, or a guest injury in your unit could lead to significant out-of-pocket expenses.
I'm Mikhail Kovalev of Kovalev Insurance Agency. For over a decade, I've helped Massachusetts condo owners find the right HO6 coverage. Protecting your investment and financial security is essential, and the right policy provides that peace of mind.
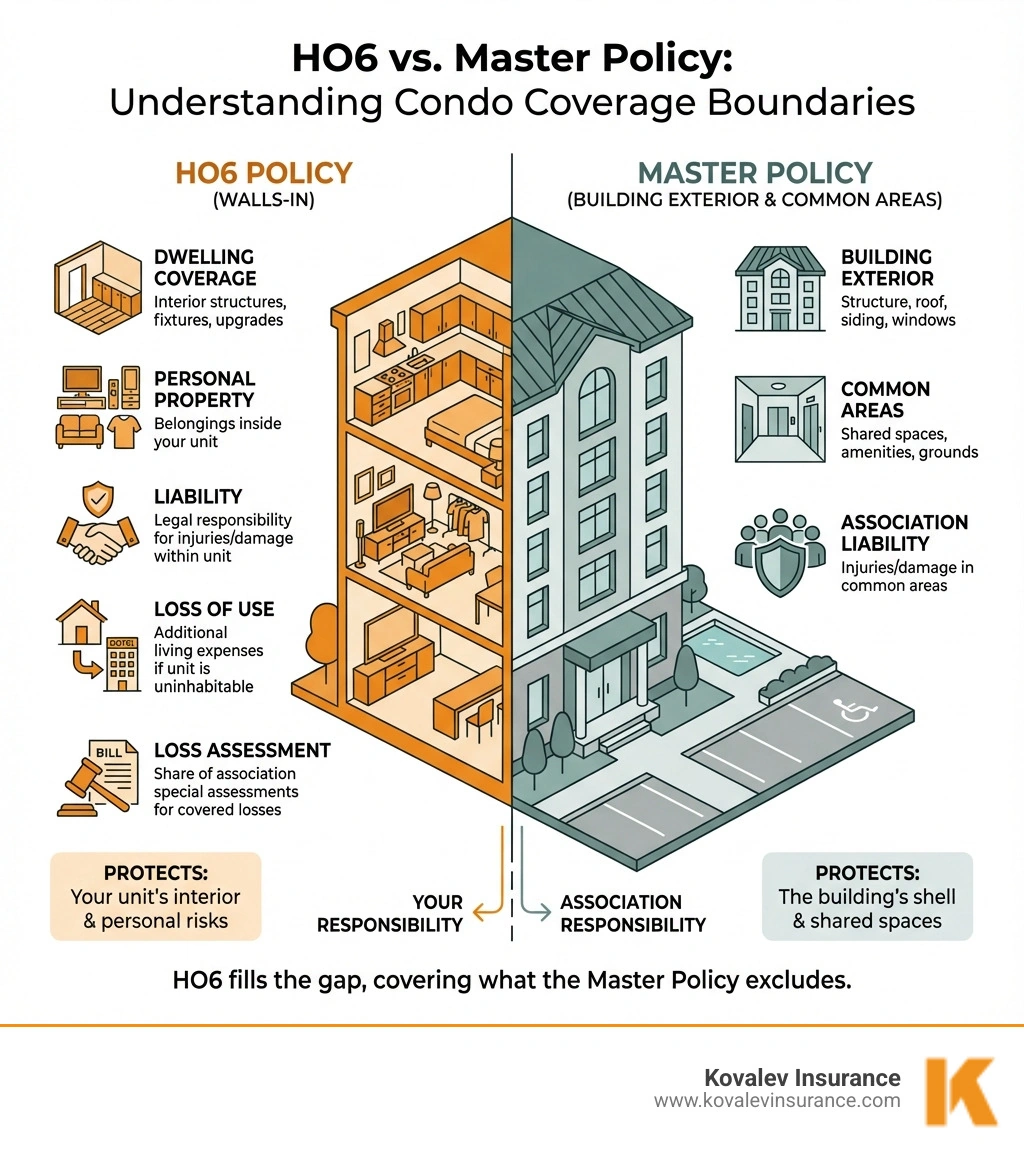
An HO6 policy, or "condo insurance," is essential for condominium and co-op owners in Massachusetts. It provides "walls-in" coverage, protecting everything within your unit where your association's master policy leaves off. It typically covers losses from specific events listed in your policy, such as fire, theft, and certain types of water damage.
If you own a condo, co-op, or some townhouses, you need HO6 insurance. Most mortgage lenders require it to protect their investment. Your condo association will also likely mandate it to protect the community from shared financial burdens. For our clients in Brookline, Newton, and Wellesley, understanding these requirements is a crucial first step. An HO6 policy is vital for protecting your personal assets from the significant financial risk of damage or liability claims.
To learn more about how this specialized coverage protects your home, check out our detailed guide on What is HO6 Condo Insurance?.
An HO6 policy is a package of coverages designed for condo owners:
Loss Assessment Coverage is a critical, often overlooked, part of an HO6 policy. If damage to a common area (like the roof) or a liability lawsuit exceeds the condo association's master policy limits, the association can levy a "special assessment" against all unit owners to cover the shortfall. This can result in an unexpected bill for thousands of dollars.
Your loss assessment coverage helps pay this bill. Standard policies often include a minimal limit (e.g., $1,000), which is frequently insufficient. We often recommend at least $50,000 in loss assessment coverage to adequately protect yourself. Dive deeper into this topic with our guide on Condo Association Insurance MA.
Your HO6 policy and the association's master policy work together. The master policy covers the building's exterior and common areas. Your HO6 covers your unit's interior. The type of master policy determines how much dwelling coverage you need.
If your Belmont condo has a "Bare Walls-In" policy, you'll need robust dwelling coverage. If it's "All-In," your needs may be lower. It's crucial to review your master policy to determine the right coverage. For a comprehensive view, see our Mass. Condo Insurance: The Ultimate Guide.
It's important to know what an HO6 policy doesn't cover. You may need separate policies or endorsements for these common exclusions:
Choosing the right HO6 policy in Massachusetts isn't just about the cheapest rate; it's about getting the right protection for your property, especially given our local climate and property values in areas like Newton and Wellesley.
Determining the right amount of coverage is key to being protected without overpaying.
How Much Does HO6 Insurance Cost in Massachusetts?
The cost of HO6 insurance varies, with national averages ranging from about $445 to $531 per year. Your actual premium in Massachusetts will depend on:
At Kovalev Insurance, we specialize in finding the best rates for our Massachusetts clients. We can provide a personalized quote that balances coverage and cost. For more on local costs, see our guides on How Much to Insure Home in Mass. and Condo Insurance Massachusetts Coverage.
We get a lot of questions about what is HO6 insurance. Here are some quick answers to the most common ones.
HO4 insurance is for renters and covers personal belongings and liability. HO6 insurance is for condo/co-op owners and covers personal belongings, liability, AND the interior structure of the unit you own.
They work as a team. The master policy covers the building's exterior and common areas. Your HO6 policy covers everything inside your unit's walls, plus your personal liability.
Common exclusions include damage to the building's exterior, floods, earthquakes, normal wear and tear, and pest infestations. Separate policies are often needed for flood and earthquake coverage.
This crucial coverage helps pay your share of a "special assessment" if a claim for a common area or a lawsuit against the association exceeds the master policy's limits.
The right amount depends on the cost to rebuild your unit's interior, the value of your personal belongings, and your total net worth (for liability). We can help you calculate the precise limits you need.
Costs vary based on your location, coverage limits, deductible, and building characteristics. In Massachusetts, we can shop multiple carriers to find you a competitive rate.
Anyone who owns a condominium unit, co-op, or certain types of townhouses needs HO6 insurance. It is often required by mortgage lenders and the condo association.
There are three main types: Bare Walls-In, Single Entity, and All-In. The type your association has dictates how much dwelling (interior structure) coverage you need on your HO6 policy. It's essential to review the master policy to avoid coverage gaps.
Navigating condo insurance, especially in a dynamic market like Massachusetts, can feel like a labyrinth. But you don't have to go it alone. We at Kovalev Insurance are passionate about simplifying insurance and ensuring our clients have robust protection.
From the historic streets of Boston to the charming communities of Newton, Wellesley, Needham, Belmont, and Natick, we understand the unique needs of Massachusetts condo owners. We offer personalized solutions, competitive rates, and the expert knowledge to guide you through every step of the process.
Don't leave your valuable investment vulnerable. Contact us today for a personalized quote and let us help you find the perfect HO6 policy that gives you peace of mind. Your condo is your sanctuary; let's protect it together.


X