Blog Content

12
Sep
2026
Wellesley is one of the most desirable communities in Massachusetts — and that comes with a price tag. Homes here carry some of the highest property values in Greater Boston, putting them in a category alongside Newton, Brookline, Needham, Belmont, and Natick. That's great for your net worth, but it also means the stakes are higher when it comes to protecting your home.
Here's the sobering part: nationally, more than half of all U.S. homes are underinsured. In a high-value market like Wellesley, that gap can translate into hundreds of thousands of dollars of exposure if disaster strikes.
Getting the right coverage at the right price isn't just about clicking the cheapest quote you see online. It's about understanding what you're actually buying — and making sure it's enough.
I'm Mikhail Kovalev, a Certified Insurance Counselor (CIC) and second-generation owner of Kovalev Insurance Agency, and I've spent years helping Massachusetts homeowners navigate home insurance quotes in Wellesley and across Greater Boston to find coverage that truly protects their most valuable asset. In this guide, I'll walk you through everything you need to compare quotes confidently and avoid the costly mistake of being underinsured.
When you look at home insurance quotes in Wellesley, you might notice the numbers look a bit different than the state average. This is largely because of the stunning real estate throughout Wellesley Hills and surrounding neighborhoods. To get an accurate estimate, you must first understand how insurers calculate your property's value.
One of the most common mistakes homeowners make is confusing market value with replacement cost.
In Wellesley, custom molding, plaster walls, historical details, and high-end masonry are common. Rebuilding these features requires specialized craftsmen and premium materials, meaning your replacement cost could easily exceed your home's market value. If you want to dive deeper into this process, check out our guide on How to Buy Homeowners Insurance in Massachusetts.
Additionally, if you have a mortgage on your home, your lender will mandate that you carry a homeowners policy. They want to ensure their financial interest is protected, but their minimum requirements often only cover the loan balance—not the actual cost to rebuild your home and replace your belongings. To ensure your coverage meets both your lender's rules and your actual protection needs, you can review the Massachusetts Home Insurance: Get a Quote Online guide.
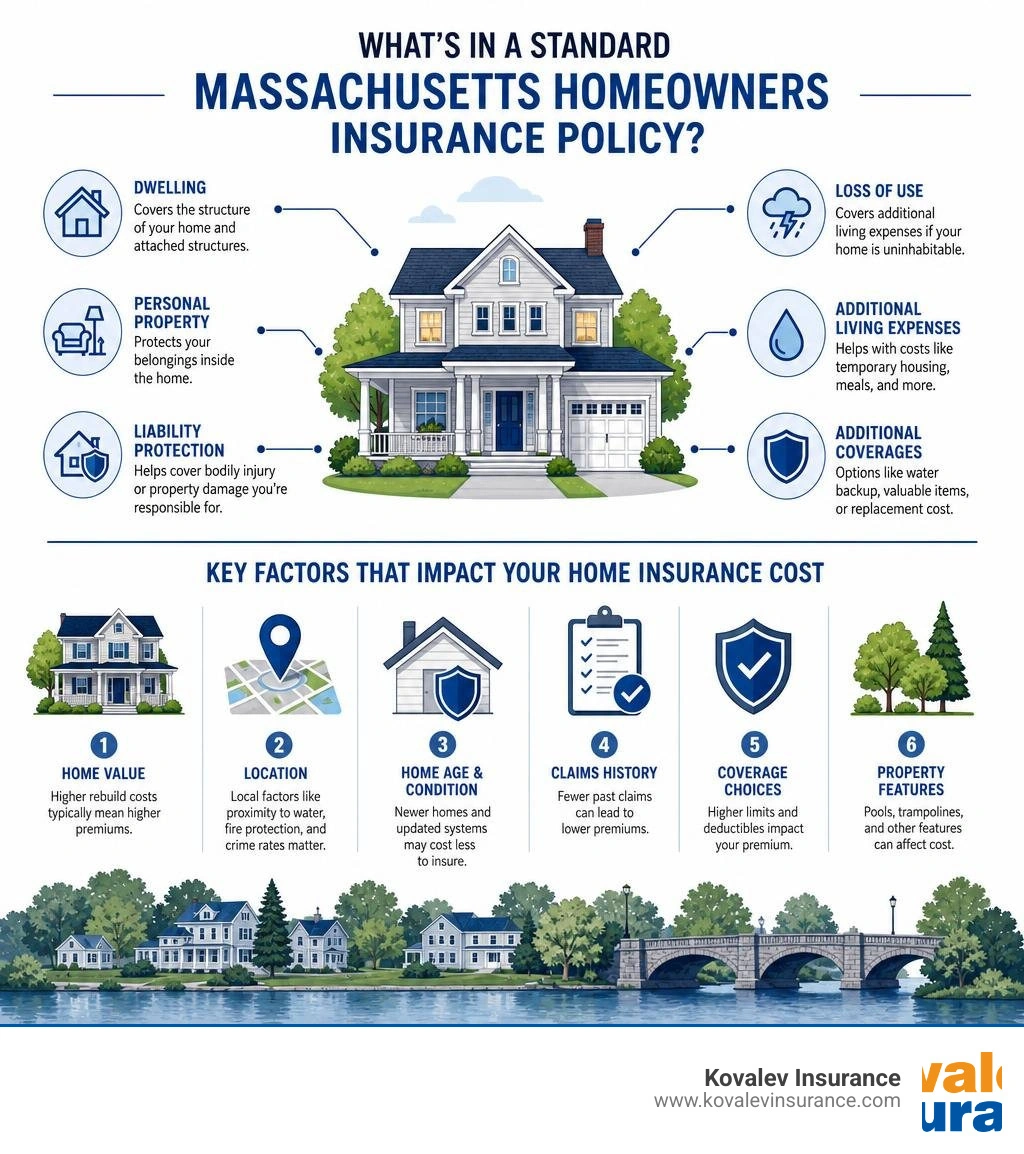
A standard Massachusetts homeowners policy (typically an HO-3 policy) is designed to protect you from a variety of unexpected disasters, such as fires, windstorms, frozen pipes, and theft. To fully understand your policy, it helps to know the main pillars of coverage:
While these standard coverages form the foundation of your protection, they don't cover everything. For instance, standard policies typically exclude water backup from drains or sump pumps. In local areas like Wellesley, Newton, and Brookline, where finished basements are highly popular, adding a water backup endorsement is highly recommended. For a complete breakdown, read our article on What Does MA Home Insurance Cover.
Insurers don't pull premium numbers out of thin air. They look at your home's unique risk profile to determine your rate.
Understanding how these elements interact is key to managing your insurance budget. You can learn more about these variables in our guide to Understand Home Insurance Costs Massachusetts.
It is just as important to know what your policy doesn't cover. Standard homeowners insurance policies in Massachusetts do not cover:
While Wellesley homes require robust coverage, you shouldn't have to pay a fortune for it. There are several highly effective ways to lower your premiums without sacrificing the protection you need.
First, consider upgrading your home’s security. Installing a burglar alarm, smart water leak detectors, or a hardwired fire alarm system that alerts local emergency services can earn you significant safety discounts. Furthermore, keeping your home well-maintained—such as updating an old electrical panel or replacing an aging roof—helps you qualify for lower rates and keeps you claims-free. Discover more about standard rates and saving opportunities in our article on the Average Cost of Home Insurance in Massachusetts.
The single most effective way to slash your insurance costs is by bundling your home and auto policies with the same insurance carrier.
In Massachusetts, bundling typically saves you 15% to 25% on your combined premiums. In addition to the direct financial savings, bundling simplifies your life. You only have to deal with one insurance agency, manage one online account, and coordinate with one team if you ever need to file a claim. To find the best bundled rates in the area, check out the Best Home Insurance Deals Massachusetts.
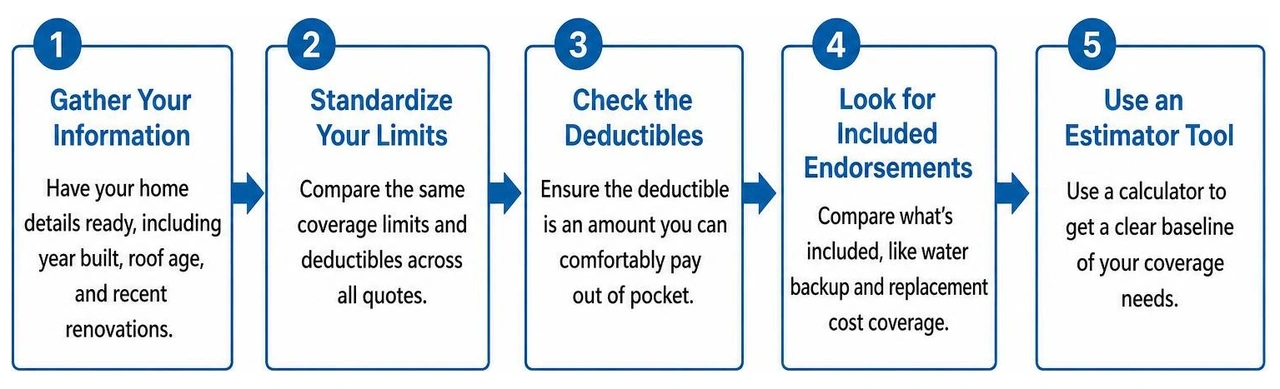
Comparing quotes should be a systematic process. Don't just look at the bottom-line price; look at what you are getting for that price.
The absolute best way to secure competitive home insurance quotes in Wellesley is to work with a local independent insurance agency. Captive agents can only sell policies from a single brand, but independent agencies work with dozens of top-rated insurance carriers to shop around on your behalf.
At Kovalev Insurance, we specialize in tailoring coverage options to meet the unique needs of homeowners in Wellesley, Newton, Brookline, Needham, Belmont, and Natick. We understand the local risks, from winter ice dams to the specific rebuilding costs of Greater Boston's historic properties. We emphasize speed, expert knowledge, and personalized service to make sure you get the best rates without any gaps in coverage.
Ready to protect your home with a policy tailored to your exact needs? Read our Massachusetts Homeowners Insurance Guide 2025 or get started today by requesting a personalized quote directly through our Kovalev Insurance Homeowners Quote Portal. Let us do the heavy lifting so you can enjoy peace of mind knowing your home is truly protected.


X