Blog Content

21
Aug
2026
Business car insurance add on coverages are optional endorsements that customize a standard commercial auto policy to address specific risks. Here's a quick look at the most common options:
A contractor's van in Wellesley, a delivery driver's personal car in Brookline, a sales rep's borrowed vehicle in Newton—these common Massachusetts business scenarios can expose you to risks your standard commercial auto policy might not cover.
Many business owners assume their commercial auto insurance covers every situation. It doesn't. A base policy typically includes liability and physical damage for owned vehicles. But what about when an employee drives their own car for a work errand, your van is in the shop, or tools are stolen from your truck?
That's where add-ons come in. They transform a basic policy into protection custom to your actual operations. The challenge is knowing which ones matter for your business in the Greater Boston area.
A standard commercial auto policy is a foundation, not a complete solution. For businesses in Massachusetts, from Newton to Natick, customizing this coverage with add-ons is essential. A base policy covers losses when driving for work, which is vital since personal auto policies exclude business use. Commercial policies have higher liability limits to protect business assets, and Massachusetts requires minimum coverage levels.
Add-ons, or endorsements, extend protection beyond the standard policy to cover specific scenarios. Tailoring this coverage to your operations is not just smart; it's essential. For a deeper dive into general commercial auto insurance in our state, refer to our guide on Commercial Auto Insurance MA Cont.
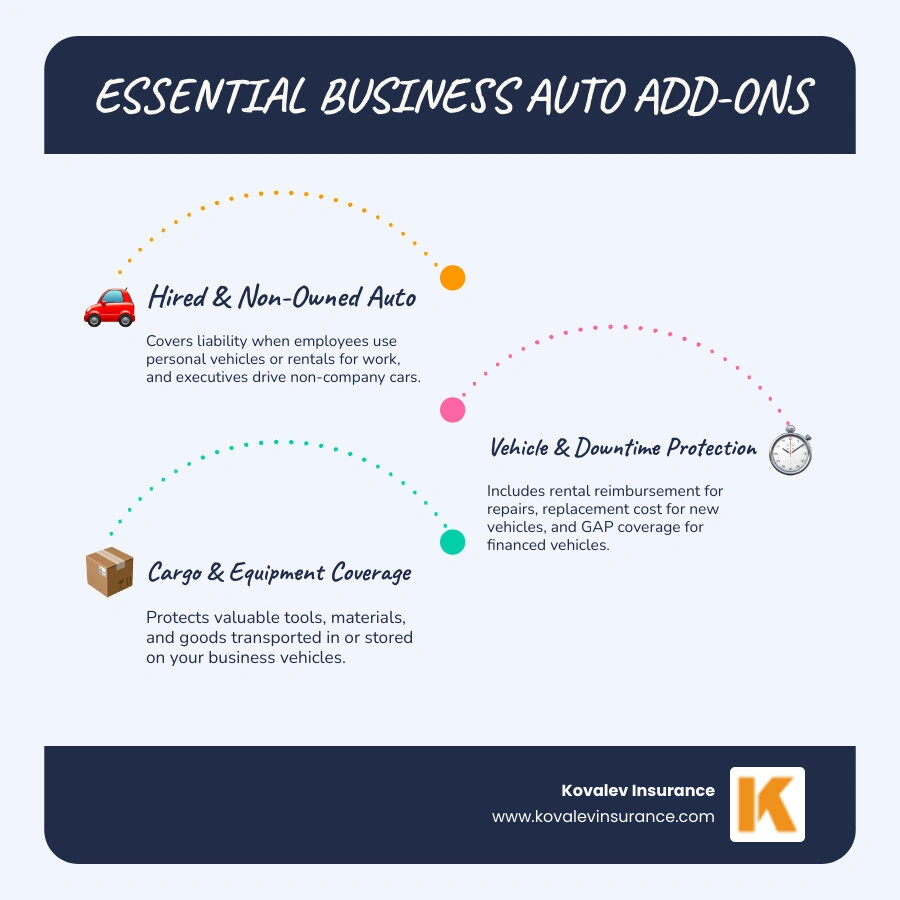
If your sales team in Brookline uses personal cars to visit clients, or you run a delivery service in Greater Boston, what happens if an employee has an accident on the clock? Their personal policy will likely deny the claim due to a "business use" exclusion, leaving your business liable. This is where Hired and Non-Owned Auto (HNOA) coverage is critical.
What is HNOA and when is it needed?HNOA is a business car insurance add on providing liability coverage for vehicles your business uses but doesn't own, including:
If employees use personal vehicles for work or you rent vehicles, HNOA is a necessity. For a detailed comparison, see our insights on Commercial Hired vs Non Owned Auto.
What is a Drive Other Car (DOC) endorsement?While HNOA covers the business's liability, the Drive Other Car (DOC) endorsement is a specialized business car insurance add on that protects specific individuals, typically a company’s executive officers and their spouses. It provides protection when they drive a vehicle the company doesn't own (and they don't have a personal auto policy), ensuring key personnel are protected.
When a business vehicle is out of commission, it's a direct hit to your bottom line. Standard policies cover physical damage but often don't account for the operational downtime. These business car insurance add on options are invaluable.
How does add-on coverage like transportation expenses work?If your primary work truck for your Wellesley landscaping business needs repairs after an accident, Rental Reimbursement (which includes Transportation Expenses) helps cover the cost of a rental vehicle so your business keeps moving.
Other vital downtime and physical damage add-ons include:
For many Massachusetts businesses, like contractors in Newton or delivery services in Boston, vehicles are mobile workshops. Your commercial auto policy covers the vehicle, not its contents. This is a common and costly coverage gap.
How do add-ons cover tools and equipment?A standard commercial auto policy covers permanently attached equipment (e.g., ladder racks), but not loose tools or materials. To protect these valuable items, you need a specialized business car insurance add on known as Inland Marine Insurance, often called a Contractors Equipment Floater.
Inland Marine Insurance / Contractors Equipment Floater:
Without it, replacing stolen or damaged equipment could create a significant financial burden. Learn more about protecting your assets on our page about the Contractors Equipment Floater. For a broader overview, the Insurance Information Institute offers excellent resources on business vehicle insurance.
For any business owner in Massachusetts, from a small shop in Natick to a large firm in Greater Boston, smart customization is key to balancing protection with cost. It’s about strategically choosing the right business car insurance add on options for your unique risks.
At Kovalev Insurance, we recommend an annual policy review to ensure your coverage evolves with your business, providing strategic protection that anticipates challenges.
Adding coverage increases your premium, but it's a calculated trade-off. The cost of a business car insurance add on depends on several factors:
Median Costs for Context:The median monthly cost for a Business Auto policy is around $219 for businesses like restaurants. For contractors in Massachusetts, the median is about $212. These are base policy figures; endorsements will increase them.
Strategies to Manage Costs:
For more cost-saving insights, explore our guide on Ways Reduce Cost Artisans Insurance.
This table shows how a business car insurance add on fills the gaps left by a standard policy.
This table clearly illustrates that while a standard policy is the base, strategic business car insurance add on options provide truly comprehensive protection.
Understanding commercial auto insurance add-ons is complex, which is why expert advice is crucial for businesses in Greater Boston. Your business in Wellesley, Newton, or Natick has unique risks that require a custom policy.
An independent agent who understands Massachusetts regulations is vital. At Kovalev Insurance, we specialize in helping businesses across our local communities of Newton, Wellesley, Needham, Brookline, Belmont, and Natick.
The Kovalev Insurance Advantage: Your Independent Agent
The policy is the foundation; add-ons are the crucial improvements that fortify your business. Don't leave your business exposed. Work with an independent agent to review your needs. For a custom approach to protecting your commercial vehicles, reach out to us. We're here to help you get the best commercial auto insurance in Mass.



X