Blog Content

8
Nov
2026
Homeowners insurance discounts can meaningfully reduce what you pay each year — and most homeowners are leaving money on the table without even knowing it.
Here are the most common discounts available to Massachusetts homeowners:
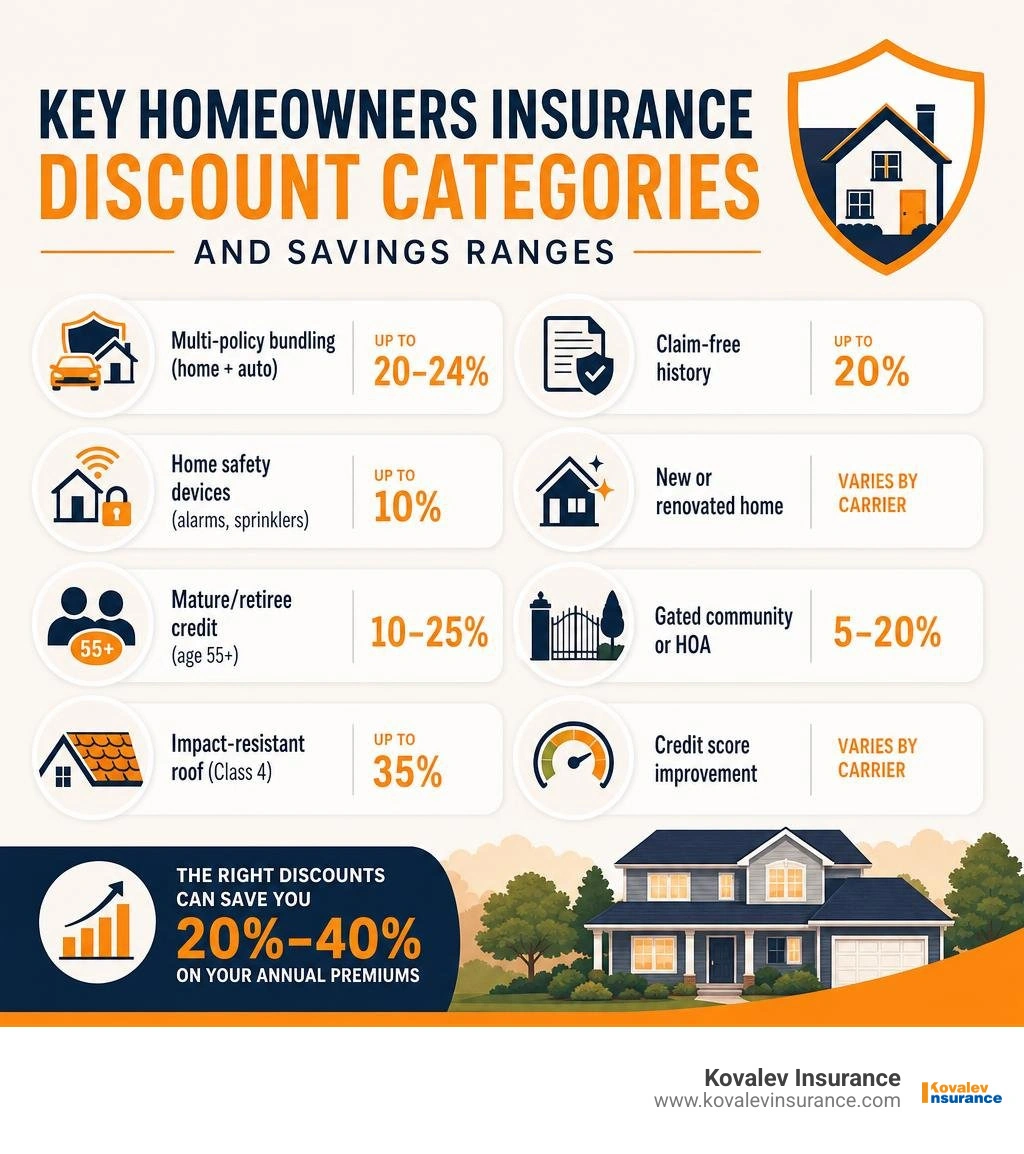
Massachusetts homeowners — especially in higher-value markets like Newton, Wellesley, and Brookline — often face above-average premiums due to rising home values and regional weather risks. The good news is that a combination of the right discounts and smart policy choices can cut those costs significantly. According to industry data, comparing quotes and qualifying for the right discounts can save homeowners between 20% and 40% on their annual premiums.
I'm Mikhail Kovalev, a Certified Insurance Counselor (CIC) and owner of Kovalev Insurance Agency, and I've spent over a decade helping Massachusetts homeowners find every homeowners insurance discount they qualify for. In the sections below, I'll walk you through exactly how to do the same.
Finding practical ways to trim policy costs without sacrificing essential coverage is easier than most policyholders realize. Insurance carriers structure their pricing around risk evaluation. When you take concrete steps to reduce the risk of structural loss, property damage, or liability claims, insurers reward you with lower annual premiums.
Whether you reside in a historic colonial in Belmont or a contemporary dwelling in Wellesley, understanding how specific premium reduction opportunities work allows you to proactively lower your costs.
One of the largest individual rate reductions available to property owners comes from policy bundling. When you combine your property insurance with an auto policy under the same carrier, insurers regularly grant a multi-policy discount of up to 20% to 24%. In fact, industry statistics show that combining property and auto coverage yields an average annualized savings exceeding $1,000. Exploring Smart Auto and Home Insurance Bundles provides an immediate path toward meaningful savings across your entire personal insurance portfolio.
Maintaining a clean claims record is another powerful mechanism for rate suppression. Insurance carriers reward homeowners who demonstrate proactive maintenance and care.
Establishing continuous prior coverage without policy gaps further reinforces your status as a reliable policyholder. To learn more about consolidating your coverage, read our guide on Master Bundle Auto and Home Insurance to see how multi-policy structures maximize annual financial retention. You can also explore general Homeowners Insurance Discounts and Savings - ValuePenguin insights to understand regional carrier strategies.
Investing in smart safety technology and structural resilience safeguards your property while generating continuous policy credits.
Modern protective devices directly offset potential insurance losses by identifying hazards before catastrophic destruction occurs:
As life circumstances evolve, additional savings opportunities open up based on demographic factors and neighborhood characteristics.
Policyholders aged 55 and older who are retired often qualify for a Mature Credit ranging between 10% and 25%. Insurance carriers recognize that retirees spend more time at home during the day. This presence allows homeowners to detect early warning signs — such as a leaking pipe, electrical spark, or heating system malfunction — before extensive property damage develops.
Community location also impacts annual pricing across Greater Boston communities:
Financial management directly influences property insurance pricing. In Massachusetts, insurance companies utilize credit-based insurance scores to evaluate risk. Maintaining low credit utilization and paying bills on time elevates your credit score, which directly correlates with lower annual policy pricing.
Adjusting your deductible strategy is another immediate tactic to lower monthly expenses. Raising your policy deductible from $1,000 to $2,500 or $5,000 reduces your baseline premium, provided you keep sufficient cash reserves set aside for unexpected emergency repairs.
Understanding coverage structures is critical when customizing your policy. The table below illustrates the primary ways carriers evaluate dwelling replacement limits:
For detailed guidance on balancing policy limits and deductibles, check our resource on Affordable Home Insurance Tips in Massachusetts.
While insurance exists to cover catastrophic events, filing minor claims for low-dollar losses often backfires financially. For example, filing a $1,250 claim with a $1,000 policy deductible results in a modest $250 payout. However, losing your claim-free discount and facing potential rate increases over subsequent renewal cycles can easily outweigh that small initial payout. Reserving claims for significant disasters while paying small maintenance repairs out of pocket preserves long-term rate stability.
To keep premiums competitive, market re-evaluation is crucial. Industry guidelines recommend conducting policy reviews and comparing market rates at least once every three years. Reviewing current coverage offerings with local independent advisors helps ensure your rates reflect modern market updates. Check out our detailed overview of the Best Home Insurance Deals in Massachusetts to see how structured comparisons yield substantial savings.
Navigating the local real estate market requires an understanding of regional weather patterns, older housing stock, and building codes specific to Newton, Wellesley, Brookline, Needham, Belmont, and Natick. Working with a dedicated independent agency like Kovalev Insurance ensures you receive objective advice tailored to your property.
We perform comprehensive policy audits to uncover overlooked savings, update outdated policy valuations, and structure multi-policy savings tailored to your exact lifestyle. To discover how much you can save on your policy without sacrificing quality protection, explore our comprehensive guide to the best homeowners insurance in Massachusetts or contact our team today to schedule your custom policy review!

X