From Offices to Warehouses: Comprehensive Commercial Property Insurance for Massachusetts Businesses

9

Aug

2026

Author:

Michael Kovalev

Why Massachusetts Commercial Property Insurance Matters for Your Business

Massachusetts commercial property insurance protects your business's physical assets—from buildings and equipment to inventory and furniture—against damage, theft, and other covered losses. Whether you own a warehouse in Natick, lease retail space in Wellesley, or operate an office in Newton, this coverage helps you recover financially when unexpected events threaten your livelihood.

Quick Answer: What You Need to Know

  • What it covers: Buildings, equipment, inventory, furniture, and business income loss
  • Who needs it: Property owners, commercial tenants, retailers, manufacturers, and home-based businesses
  • Cost: Typically $45/month or less for 56% of small businesses, varying by location and risk factors
  • Requirements: Not legally required in Massachusetts, but often mandatory for leases and SBA loans
  • Policy types: Basic (fire only), Broad (fire + theft + limited perils), or Special (all-risk coverage)
  • Key exclusions: Floods and earthquakes require separate policies

Massachusetts businesses face unique risks. Winter storms can damage roofs with heavy snow loads. Coastal areas like parts of Newton and Brookline face wind and water risks. Urban properties deal with higher liability exposure from foot traffic. And aging buildings throughout Greater Boston may need special consideration for renovation costs after a loss.

The challenge? Finding coverage that actually fits your specific property, location, and budget—without overpaying or leaving dangerous gaps.

I'm Mikhail Kovalev, and I've helped grow Kovalev Insurance from a three-person team to a 20-person agency writing over $20 million in premium volume, insuring more than $1 billion of real property across Massachusetts. Over nearly a decade specializing in Massachusetts commercial property insurance, I've seen how the right coverage protects businesses in Newton, Wellesley, Brookline, Needham, Belmont, and Natick from devastating financial losses.
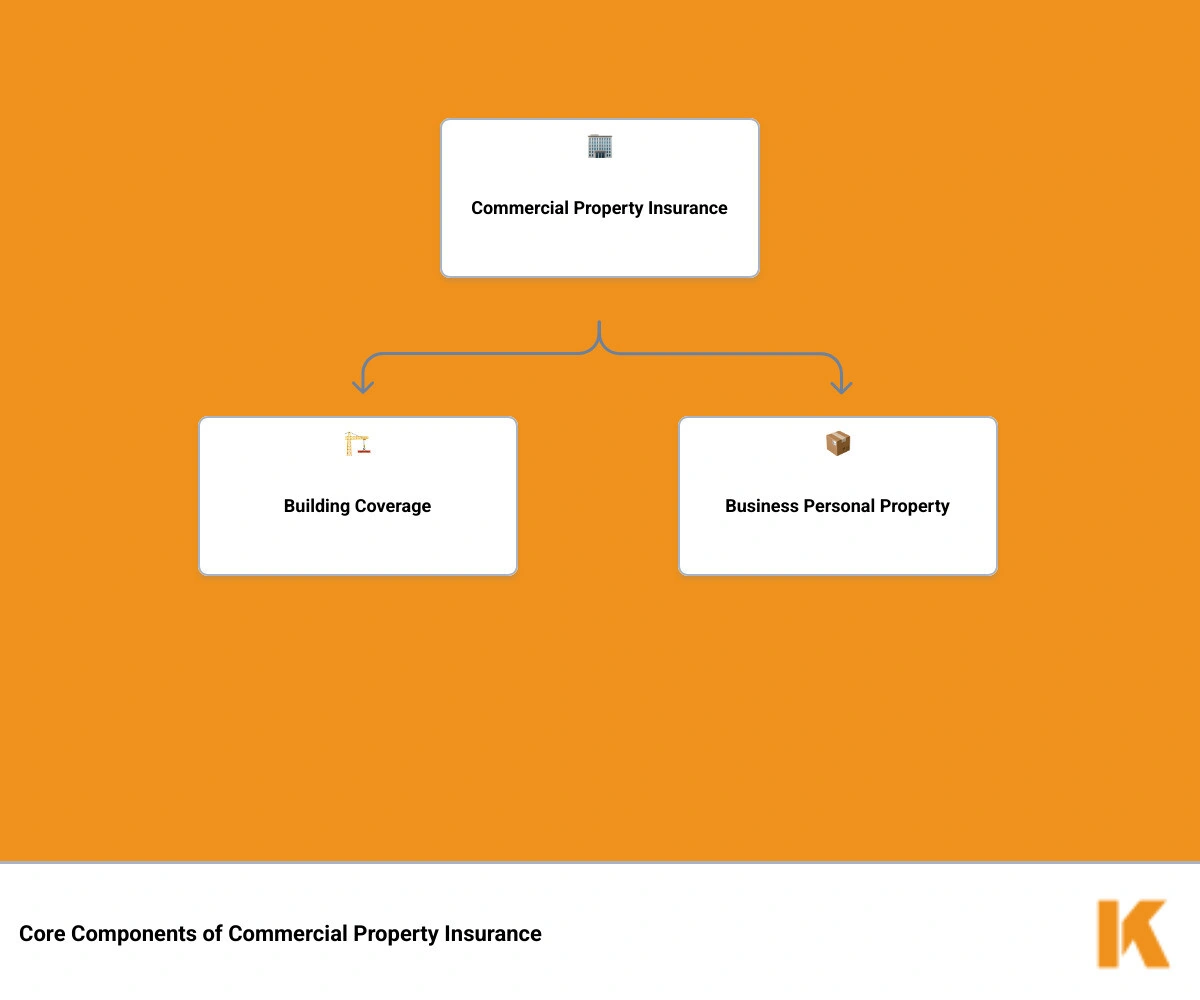
Infographic showing the core components of a Massachusetts commercial property insurance policy: building coverage protecting structure and fixtures, business personal property covering equipment and inventory, business income coverage for lost revenue during repairs, and optional add-ons like equipment breakdown and debris removal - massachusetts commercial property insurance infographic hierarchy

Understanding Massachusetts Commercial Property Insurance

When we talk about commercial property insurance mass, we are looking at the financial safety net for the "stuff" your business owns or uses. In a state like Massachusetts, where property values are high and the weather is unpredictable, this isn't just a luxury; it's a fundamental part of your business plan.
modern warehouse facility in Natick Massachusetts - massachusetts commercial property insurance

Building Structures

If you own your building in Natick or Needham, this coverage protects the physical structure itself. This includes everything from the foundation and walls to the roof and permanently installed fixtures. If a fire breaks out or a heavy snow load causes a collapse, your policy helps pay for the repairs or rebuilding.

Business Personal Property (BPP)

What if you rent your space? You still have a massive investment inside those walls. Business Personal Property covers the items you use to run your business. This includes:

  • Equipment and Machinery: From the high-end ovens in a Belmont bakery to the specialized diagnostic tools in a Newton medical office.
  • Inventory: The finished products on your shelves and the raw materials in your warehouse.
  • Furniture: Desks, chairs, and shelving units.
  • Electronics: Computers, servers, and telecommunications gear.

Valuation: Actual Cash Value vs. Replacement Cost

One of the most important lessons we teach our clients is the difference between how your property is valued. This can make or break your business after a claim.

Feature Actual Cash Value (ACV) Replacement Cost (RC)
Definition The cost to replace the item minus depreciation. The cost to buy a new version of the same item today.
Payout Lower (based on current "used" value). Higher (covers the full price of new items).
Premium Generally lower premiums. Generally higher premiums.
Best For Businesses with limited budgets or older assets. Most businesses that need to get back to work quickly.

Who Needs Massachusetts Commercial Property Insurance?

It is a common misconception that only "big" companies need this. In reality, almost every business in the Greater Boston area should have some form of property protection.

  • Property Owners: If you own a commercial building in Brookline or a strip mall in Natick, you are responsible for the structure.
  • Commercial Tenants: Most leases in Wellesley or Newton require you to carry insurance for your own equipment and often include a requirement to protect the "improvements and betterments" you've made to the space.
  • Retailers: With high inventory turnover, retailers need to ensure their stock is protected from theft, fire, and water damage.
  • Manufacturers: Specialized machinery is expensive and often has long lead times for replacement.
  • Home-Based Businesses: Your standard homeowners policy likely excludes business property. If you run a consulting firm from your home in Belmont, your business laptops and equipment need a dedicated business insurance agency in Newton to help you find the right rider or standalone policy.

Coverage Types: Open-Perils vs. Named-Perils

When we look at massachusetts commercial property insurance policies, we see three main "forms" that determine what is actually covered.

  1. Basic Form: This is the most restrictive. It covers specific, named perils like fire, lightning, and explosions. If it isn't listed, it isn't covered.
  2. Broad Form: This adds a few more named perils, such as falling objects, the weight of ice and snow (very important for Natick and Belmont winters!), and water damage from accidental discharge.
  3. Special Form (Open-Perils): This is the gold standard. Instead of listing what is covered, it covers everything unless it is specifically excluded. This provides the broadest protection for your business.

Common exclusions in almost all property policies include war, nuclear hazard, and government seizure. However, the biggest exclusions for Massachusetts business owners are floods and earthquakes. We always recommend checking the FEMA Flood Map Service Center to see if your property in Newton or Brookline sits in a high-risk zone.

Key Factors Influencing Your Massachusetts Commercial Property Insurance Cost

We often get asked, "How much will this cost me?" While statistics show that many small businesses pay $45 or less per month, your specific rate depends on several "rating factors" that underwriters look at:

  • Location: A storefront in a high-traffic area of Wellesley may have different risks than a quiet office in Needham.
  • Building Age and Construction: Older buildings in Greater Boston often have higher premiums because their wiring or plumbing may be outdated. Using fire-resistive materials can lower your costs.
  • Safety Features: Do you have a central station burglar alarm? Is your warehouse in Natick equipped with a modern sprinkler system? These "preventive measures" are great for your safety and your wallet.
  • Claims History: Just like auto insurance, a history of frequent claims can drive up your premiums.
  • Deductibles: Choosing a higher deductible (the amount you pay out of pocket) will lower your monthly premium, but you must ensure you have the cash on hand to cover it if a loss occurs.

In Massachusetts, massachusetts commercial property insurance is not required by state law. However, you will find that it is almost impossible to operate without it. Lenders will require it before approving a mortgage, and the Small Business Administration (SBA) requires hazard insurance on any property used as collateral for a loan.

Beyond the "must-haves," there are several coverages that we consider essential for any business in the Newton or Natick area:

Business Income Interruption

If a fire burns down your shop in Belmont, insurance will pay to rebuild it. But how do you pay your bills while the construction is happening? Business Income insurance replaces your lost profits and helps you pay ongoing expenses like payroll and taxes while your doors are closed.

Equipment Breakdown

Standard property insurance covers external damage (like a fire). It usually does not cover internal damage (like a power surge blowing out your server or a mechanical failure in your HVAC system). Equipment breakdown coverage fills this gap.

Debris Removal and Building Codes

After a major loss, the cost of hauling away the charred remains of a building can be staggering. Furthermore, if you are rebuilding an older property in Brookline, you may be required to bring the entire structure up to modern building codes. Many of our policies include "Ordinance or Law" coverage to help pay for these unexpected expenses.

If you ever find yourself facing a loss, we are here to help. While we manage your policy, some specific state-backed programs like the MPIUA (Fair Plan) have their own processes. You can report a claim to MPIUA if you are covered under that specific program.

Location-Specific Risks: From Coastal Storms to Urban Liability

Massachusetts is a diverse state, and your insurance needs change depending on which side of Route 128 you are on.

  • Boston and Brookline Density: In these urban areas, the risk of fire spreading from a neighboring building is higher. There is also a significant risk of water damage from burst pipes in older, multi-story buildings. For more localized advice, check out our Belmont commercial insurance guide.
  • Wellesley and Needham Storefronts: These areas see high foot traffic. While property insurance covers the building, you must ensure your policy is bundled correctly with liability to protect against "slip and fall" incidents on icy sidewalks.
  • Natick and Western Suburbs: Here, snow loads are a major concern. A heavy February storm can easily collapse a flat warehouse roof if it isn't properly maintained and insured.

Essential Add-Ons and Exclusions

To truly have "comprehensive" coverage, you often need to look beyond the standard policy.

  • Flood Insurance: As mentioned, this is almost always excluded. If your business is near the Charles River or in a low-lying area of Newton, a separate flood policy is a must.
  • Inland Marine: Don't let the name fool you—it has nothing to do with the ocean. This covers your tools, equipment, and inventory while they are in transit or at a job site. This is vital for contractors in Natick or delivery services in Wellesley.
  • Builder’s Risk: If you are currently building a new facility or doing a major renovation, you need specialized coverage for the materials and labor until the project is complete.

Our team of commercial insurance specialists can help you identify which of these add-ons are necessary for your specific industry.

Securing Your Quote with Kovalev Insurance

At Kovalev Insurance, we don't believe in "one size fits all" insurance. We are independent agents, which means we work for you, not the insurance companies. We take the time to understand your business—whether it's a small boutique in Wellesley or a large manufacturing plant in Natick.

We emphasize speed, expert knowledge, and local expertise. Our headquarters in Newton puts us right in the heart of the community we serve. We know the local building codes, we understand the Massachusetts weather, and we know exactly what local landlords and lenders are looking for in a certificate of insurance.

Don't leave your life's work to chance. Continuous coverage is vital; even a one-day lapse in insurance can lead to higher premiums in the future and leave you vulnerable to a catastrophic loss.

Ready to protect your investment? Get a commercial business insurance quote today and let us show you why so many Greater Boston businesses trust Kovalev Insurance for their massachusetts commercial property insurance needs. We look forward to helping you secure the future of your business.

Blog Content

Contact Massachusetts business and Personal insurance Agency