The Definitive Guide to Comparing General Liability Insurance Massachusetts
9
Sep
2026
Author:
Michael Kovalev
Understanding General Liability Insurance in the Bay State
General liability insurance massachusetts is crucial protection against third-party claims for bodily injury, property damage, and personal or advertising injury. Whether you run a tech startup in Needham or a restaurant in Belmont, accidents can happen, and this insurance acts as a financial safety net, covering legal costs, medical bills, and settlements.
Is General Liability Insurance Legally Required in Massachusetts?
However, it's often a practical necessity due to contractual requirements:
Landlords: If you rent commercial space in Boston or surrounding towns, your lease will likely require it.
Client Contracts: Many clients, especially for contractors and consultants, will not sign a contract without proof of coverage.
Licenses and Permits: Certain trades may need it to get permits or bid on jobs.
Operating without it is a significant risk. It's less about legal obligation and more about essential risk management and professionalism for business owners in towns like Belmont and Natick.
What General Liability Insurance Covers
Think of general liability insurance massachusetts as your shield against common accidents. It typically covers:
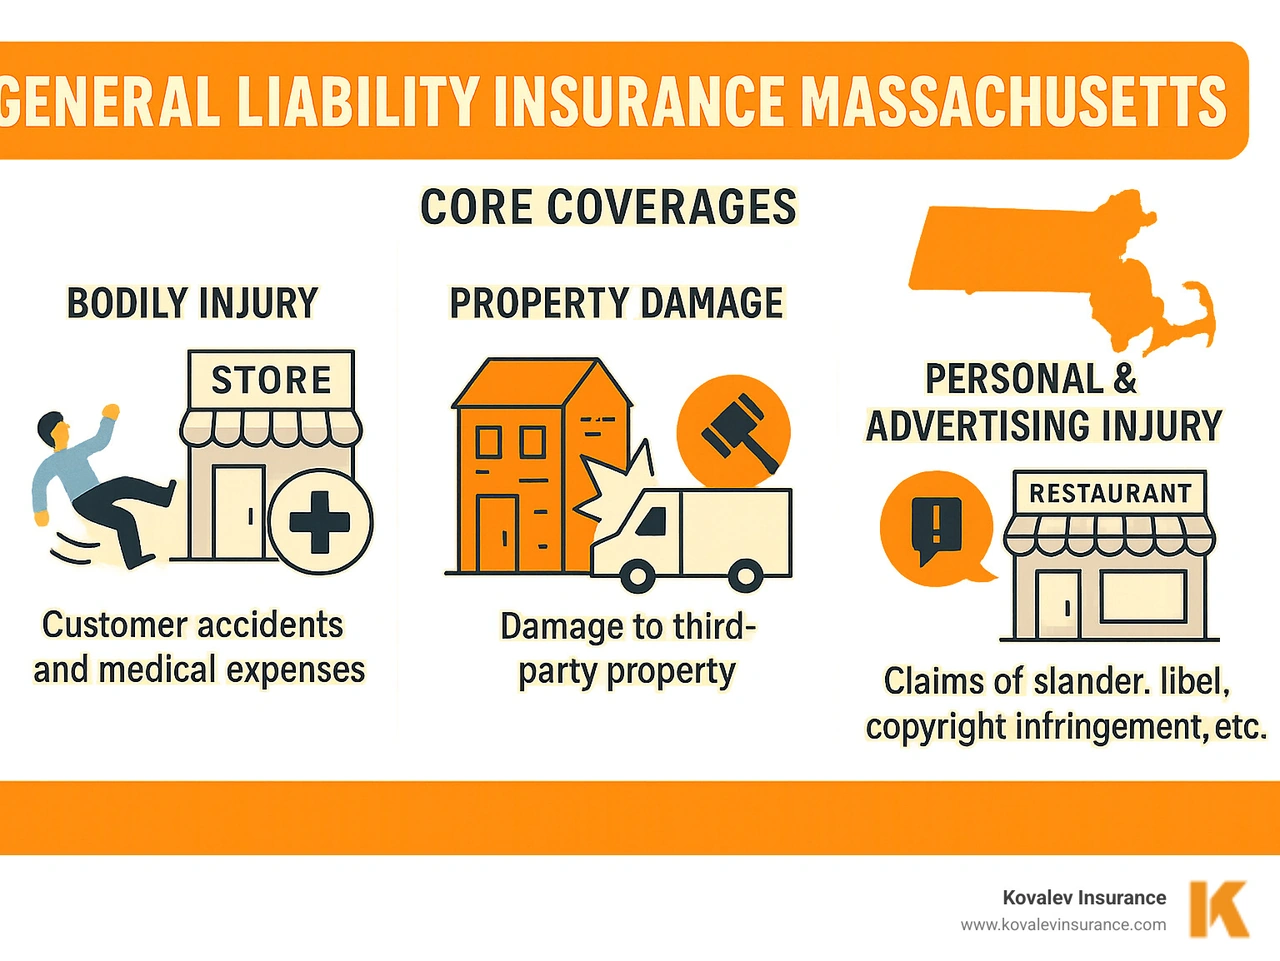
Bodily Injury: Protects you if a non-employee is injured on your premises, like a customer slipping in your Newton store. It can cover their medical expenses and your legal fees.
Property Damage: Covers costs if your business accidentally damages someone else's property. For example, if a contractor in Wellesley damages a client's flooring.
Personal & Advertising Injury: Protects against non-physical harm claims, such as libel, slander, or copyright infringement in your marketing materials.
Legal Defense Costs: A key benefit is coverage for attorney fees and court costs to defend against a lawsuit, even if it's baseless.
What General Liability Insurance Doesn't Cover
It's just as important to know the common exclusions:
Professional Errors: Mistakes in your professional services require a separate Professional Liability (E&O) policy.
Employee Injuries: On-the-job injuries to your staff are covered by workers' compensation insurance, which is required by law in Massachusetts for most employers. Learn more at Workers' Comp in Massachusetts(Mass.gov).
Auto Accidents: Business-related vehicle accidents fall under a commercial auto policy.
Damage to Your Own Property: You need commercial property insurance to cover your own building, equipment, or inventory.
Intentional Acts & Cyber Attacks: Deliberate harm and data breaches are not covered and require their own specific policies.
Shopping for general liability insurance massachusetts isn't just about finding the lowest price. The cheapest policy can have coverage gaps that leave your Newton or Brookline business exposed. The goal is to find the right balance between comprehensive protection and cost.
When comparing policies, look beyond the sticker price and focus on these key elements:
Coverage Limits: This is the maximum your insurer will pay per claim. A $1 million limit might seem high, but a contractor working on high-value properties in Wellesley may need more.
Deductibles: This is what you pay out-of-pocket before coverage kicks in. A higher deductible lowers your premium, but ensure it's an amount you can comfortably afford.
Policy Exclusions: Scrutinize what isn't covered. Some policies have industry-specific exclusions that could be problematic. For example, a landscaper in Needham should ensure tree work isn't excluded.
Key Factors That Influence Your Insurance Costs in Massachusetts
Several factors determine your general liability insurance massachusetts premium. Understanding them can help you manage your costs.
Industry Risk: This is the biggest driver. A roofing contractor in Boston faces higher risks and costs than a home-based consultant in Belmont. High-risk industries include construction, restaurants, and landscaping.
Location: Operating in a dense urban area like downtown Boston typically costs more than in a quieter suburb like Needham due to higher foot traffic and legal costs.
Business Size and Revenue: More revenue, customers, and employees mean more exposure and a higher premium.
Claims History: A clean record can lead to discounts, while a history of frequent claims will increase your rates.
Coverage Limits & Deductibles: Higher limits increase your premium, while a higher deductible will lower it. It's a direct trade-off based on your risk tolerance.
General Liability vs. Other Essential Business Coverages
General liability is a vital tool, but it doesn't cover everything. It's crucial to understand how it fits with other policies to avoid dangerous gaps in your protection.
Professional Liability (E&O): While general liability covers physical risks like accidents, professional liability covers financial losses caused by mistakes in your services. A consultant in Brookline whose advice leads to a client's financial loss would need this coverage.
Business Owner's Policy (BOP): A BOP is a convenient package for many small businesses. It bundles general liability with commercial property insurance (protecting your building and equipment) and business income coverage (covering lost revenue if you have to close temporarily). A retail store in Newton is a perfect candidate for a BOP, as it combines the key coverages they need at a potentially better price.
Not all businesses qualify for a BOP, especially those in high-risk fields. The key is to match your insurance portfolio to your specific risks. For more on comprehensive protection, explore our guide on Read about Commercial Business Owner Insurance Mass.
You've learned the essentials of general liability insurance massachusetts and are ready to secure a policy that fits your business. At Kovalev Insurance, we've guided thousands of business owners in Brookline, Newton, and across the state through this process, ensuring they get comprehensive protection without overpaying.
Getting an accurate quote is straightforward if you have your information ready. To get started, you'll generally need:
Business Details: Your legal business name, address, and structure (e.g., LLC, sole proprietor).
Operations: A clear description of what your business does.
Business Size: Annual revenue, payroll, and number of employees.
Coverage Needs: The coverage limits you desire.
Claims History: Any previous general liability claims.
While online quote tools can provide a quick estimate, working with an agent offers personalized guidance. An agent can help you spot potential coverage gaps and find discounts you might otherwise miss. When you're ready for a quote custom to your business, we can help you get covered quickly and thoroughly.
Working with an independent local insurance agent offers significant advantages over going directly to a single insurance company. As independent agents, we aren't tied to one carrier. This allows us to shop the market on your behalf, letting multiple top-rated insurers compete for your business to find the best combination of coverage and price.
Our local knowledge of the Massachusetts market is a key asset. We understand the unique risks facing a business in downtown Boston versus one in a suburb like Wellesley or Needham. This expertise allows us to provide personalized advice, ensuring your policy is custom to your specific operations.
Most importantly, we act as your advocate. From finding the right policy to providing claims assistance and ongoing support, we're your long-term partner. Your business will grow and change, and we'll be there to ensure your insurance evolves with it.
Don't leave your business vulnerable. Let us help you find the right protection.
Protect your Massachusetts lawn care business. Discover why general liability insurance for lawn care business is essential for peace of mind and growth.