Blog Content

2
Nov
2026
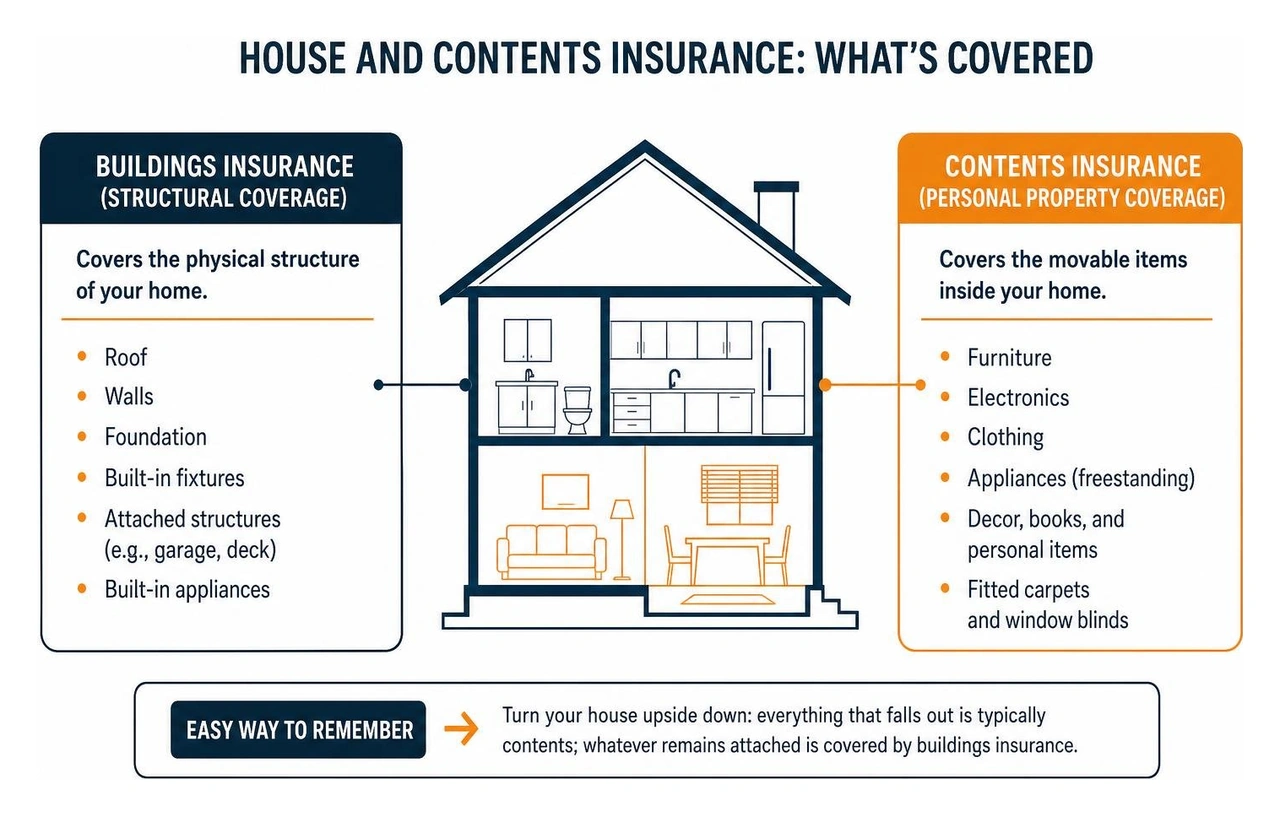
When evaluating house and contents insurance, it is essential to understand where structural coverage ends and personal property coverage begins. Buildings insurance (dwelling coverage) pays to repair or rebuild the physical structure of your property—including the roof, foundation, walls, and attached fixtures like cabinets and fitted bathroom suites. Contents insurance, on the other hand, covers the movable items inside your home, such as clothing, electronics, furniture, and freestanding appliances.
A simple way to distinguish between the two is to imagine turning your house upside down: everything that falls out is typically considered contents, while whatever remains attached belongs to the building coverage. Interestingly, items like fitted carpets and window blinds are generally classed under contents coverage rather than structural insurance.
When an unexpected disaster strikes—such as a severe fire or roof collapse from winter snow loads—your home may become unlivable. Standard combined policies include loss of use or temporary accommodation coverage. Depending on the tier of policy you select, temporary housing costs can be covered for 12 to 24 months (or up to 10% to 20% of your total sum insured), ensuring your family has a safe place to stay during major repairs. To learn more about standard policy options, explore comprehensive policy options and tier comparisons.
Insurance policies are categorized into standard policy forms designed for specific home types and coverage needs:
Policies operate under either named-peril rules (covering only events explicitly listed in the contract) or open-peril rules (covering all risk events unless the policy specifically excludes them).
Standard house and contents insurance provides vital protection, including personal liability coverage (typically up to $300,000 or more to guard against third-party bodily injury or property damage lawsuits) and specialized allowances like food spoilage coverage (reimbursing $500 to $2,000 if your refrigerator stops working after an insured event).
However, policyholders must be aware of strict standard exclusions:
For exact coverage parameters, review standard home policy terms and exclusions.
Setting your sum insured accurately is critical to avoid being underinsured. The sum insured should reflect what it would cost to rebuild your home brand new today and buy all your personal items at current retail prices—not what you originally paid for them.
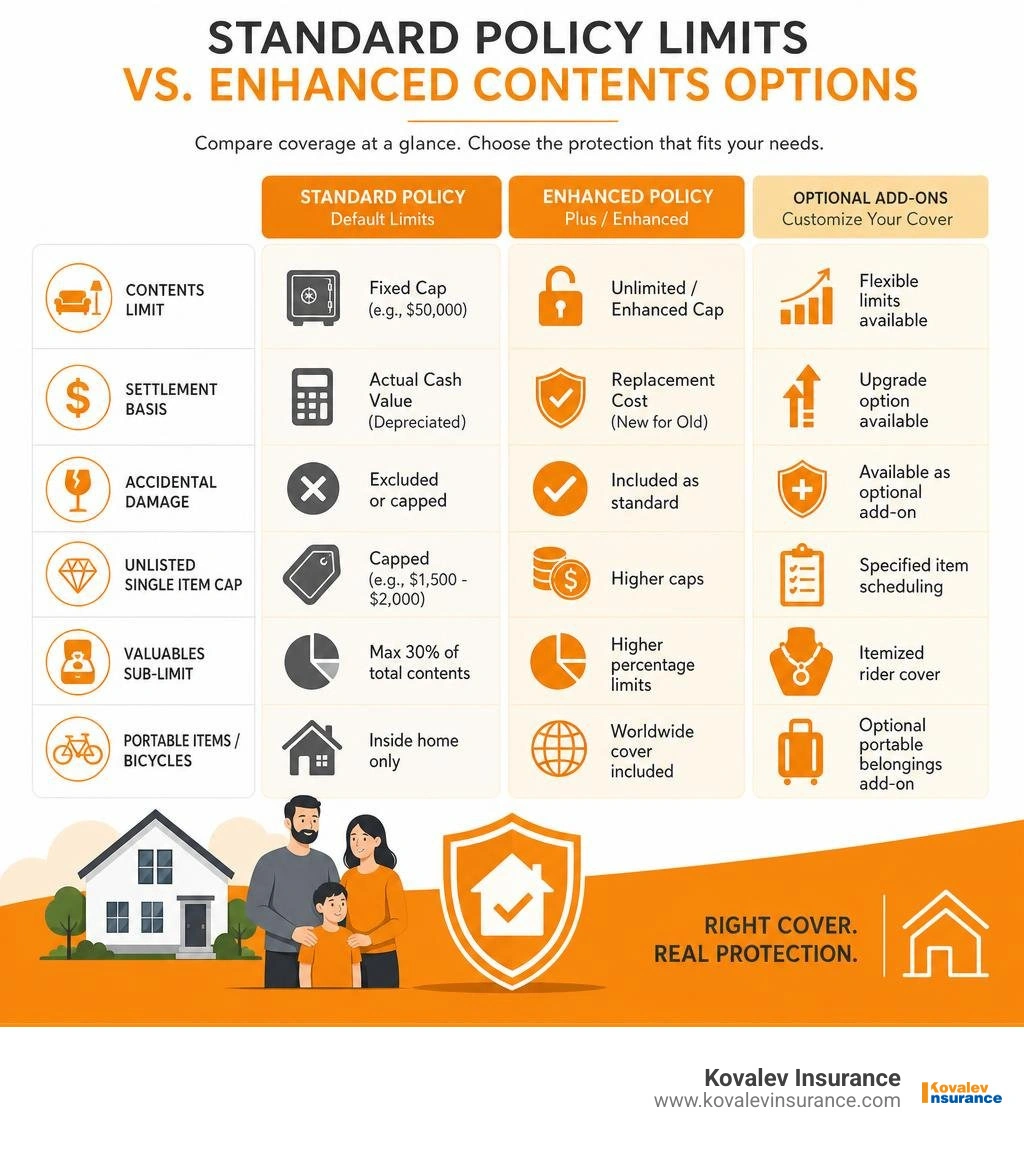
Standard policies settle claims based on actual cash value (deducting depreciation for age and wear), whereas enhanced policies use replacement cost (paying to replace the item with a brand new equivalent). If you own high-value bicycles (often requiring Sold Secure Gold or Diamond-rated locks when left unattended), fine art, or jewelry, scheduling these as specified items ensures full reimbursement. To evaluate combined features, check combined property coverage features.
If you hold a mortgage on your property in Wellesley, Brookline, or Needham, your lender will mandate continuous buildings insurance to protect their financial interest. If your coverage lapses, your lender has the legal right to institute lender-placed (force-placed) insurance. This force-placed coverage is significantly more expensive than standard policies and protects only the lender's structural risk—providing zero coverage for your personal contents or personal liability.
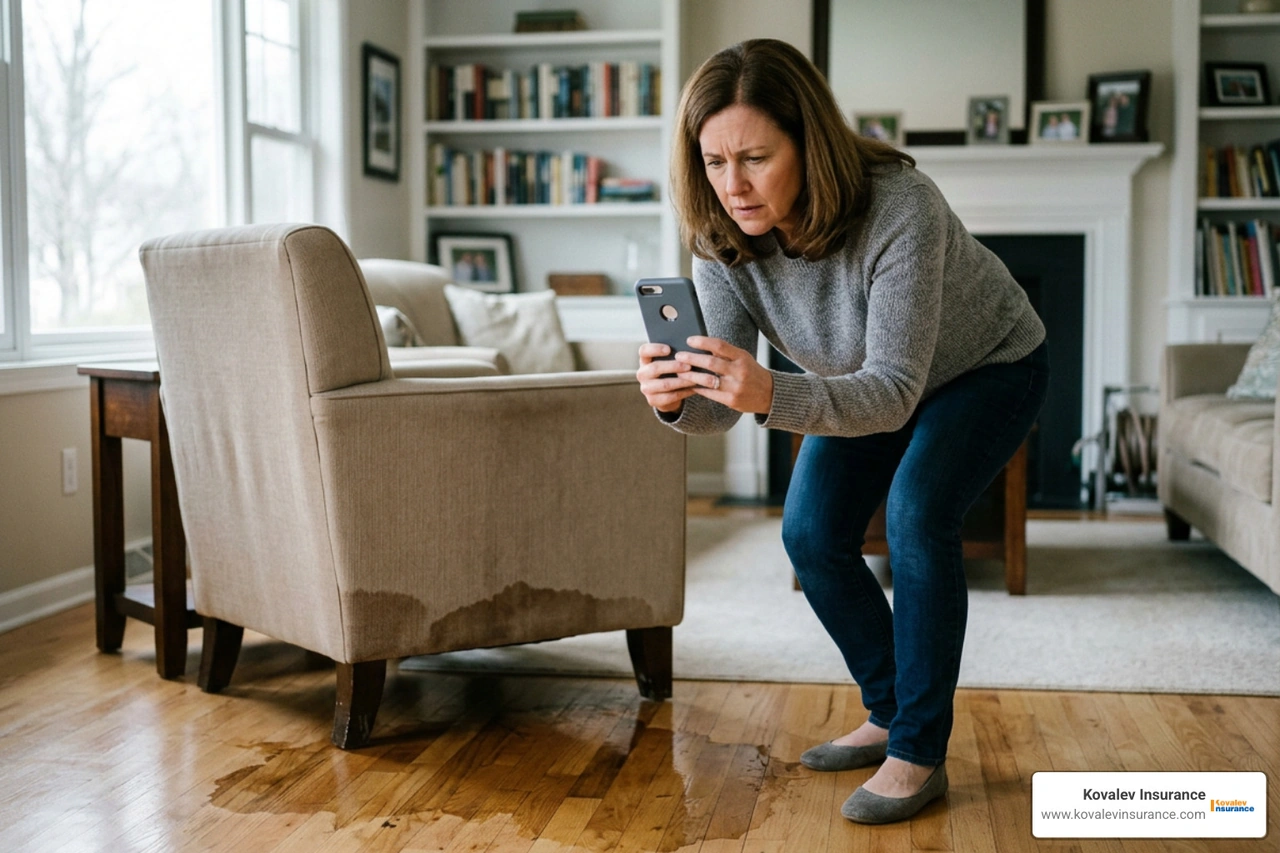
When applying for or renewing a mortgage, your bank will request a certificate of currency (or binder) to prove active, compliant coverage.
Steps to Take When Making a Claim:
Living in Massachusetts presents unique weather challenges. Severe New England winter freezes cause widespread burst pipes and roof ice dams, while seasonal coastal weather systems bring driving wind and heavy rain.
At Kovalev Insurance, we provide personalized personal and commercial insurance solutions across Newton, Wellesley, Needham, Brookline, Belmont, Natick, and the Greater Boston area. We specialize in tailored coverage options and competitive rates, emphasizing fast service and expert industry knowledge.
Whether you need to review your structural rebuilding limits, update personal belongings schedules, or secure specific endorsements for local winter perils, we are here to ensure your entire property is properly protected. Contact us today to explore the best homeowners insurance in Massachusetts for your home.

X